Trusted bad faith insurance lawyers serving clients across Fort Lauderdale and the surrounding area.
If your insurance company has unreasonably denied, delayed, or undervalued a claim it should have paid, our Fort Lauderdale, FL bad faith insurance lawyer can hold the carrier accountable for that conduct. The People's Law Team, PA Property Damage Lawyers stands with policyholders, never the companies that fail them. We handle these cases on contingency, which means no out-of-pocket legal costs and no fee unless we recover for you. Contact our office today for a free review of your situation.
Bad Faith Insurance Lawyer Fort Lauderdale, FL
Bad faith refers to an insurer's failure to handle a valid claim honestly and fairly. Every policy carries an implied duty of good faith, which requires the company to investigate promptly, evaluate the loss reasonably, and pay what it owes without unjustified delay or denial. When a carrier disregards that duty, the policyholder may have a claim that extends beyond the policy itself.
These cases differ from an ordinary coverage dispute. A bad faith claim looks not only at whether the loss was covered but at how the company treated the policyholder during the process. A Fort Lauderdale bad faith insurance attorney examines the carrier's conduct, documents the pattern of unreasonable claim handling, and pursues the consequences that Florida law makes available when an insurer acts in bad faith.
Types of Bad Faith Insurance Cases We Handle in Fort Lauderdale
Bad faith can surface in many forms, and the specific conduct shapes the claim. We represent homeowners and business owners whose insurers placed their own interests ahead of the obligations they owed. The matters below reflect the bad faith disputes our firm addresses most often for clients in the area.
- Property damage. When a carrier mishandles a covered loss to a home or commercial building, bad faith often follows the underlying dispute. We document both the damage and the unreasonable conduct that accompanied the claim.
- Insurance claims. A first-party claim handled in bad faith can leave a policyholder without the payment the policy promised. We pursue the original coverage along with the carrier's failure to honor its duty of good faith.
- Hurricane damage. Storm claims draw scrutiny, and carriers sometimes use that scrutiny as cover for unreasonable delay or denial. We establish the storm as the cause and challenge the conduct that followed.
- Water damage. Disputes over the source of a leak can become grounds for a carrier to stall a clearly covered loss. We address both the coverage question and any bad faith handling tied to the water damage.
- Unreasonable denials. A denial without a sound basis in the policy or the facts may amount to bad faith. We analyze the grounds behind denied claims and build the record showing the decision was not made in good faith.
- Unjustified delays. A carrier that lets a valid claim sit without action can cause real harm to a family or business. We document the timeline and pursue the consequences of unwarranted delay.
- Lowball settlement offers. An offer far below the true value of a covered loss can reflect a failure to evaluate the claim reasonably. We compare the offer against an independent assessment and challenge the underpayment.
- Failure to investigate. An insurer that ignores evidence or declines to conduct a proper investigation may breach its duty of good faith. We show where the carrier fell short of the standard the law requires.
Why Choose The People's Law Team, PA Property Damage Lawyers as my Bad Faith Insurance Lawyer in Fort Lauderdale, FL?
Experience That Reaches Inside the Carrier's Playbook
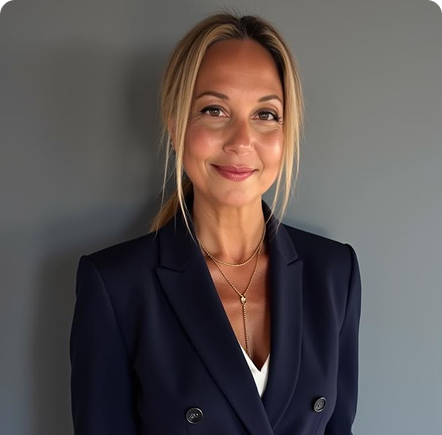
Our founder, Maria O'Donnell, spent years handling sensitive Special Investigation Unit matters for major insurers, including State Farm, Allstate, Citizens, Universal Property, Mercury, and Travelers. That work gave her a direct view of how carriers evaluate claims and where their handling can cross the line into bad faith. She now applies that knowledge on behalf of Florida policyholders. Admitted to the Florida Bar in 2002 and also licensed in Washington, D.C., she has concentrated on insurance matters for more than two decades since earning her law degree from Brooklyn Law School.
A Record of Results and No Fee Unless You Recover
We have secured millions of dollars for Florida policyholders whose claims were mishandled, built on a refusal to let carriers wear clients down. Every matter proceeds on contingency. There is no retainer, no hourly billing, and no fee at all unless we recover in your case. That structure allows homeowners and business owners to confront national insurers without staking their own resources during a difficult time.
What Is Important To Understand About Bad Faith Insurance Cases?
Bad faith claims are more demanding than a straightforward coverage dispute. They require proof not just of a covered loss but of conduct that fell below the standard the law imposes on insurers. Understanding that framework helps you recognize when a carrier's behavior may give rise to a claim.
Conduct, Duty, and Remedies in Bad Faith Cases
Most bad faith disputes turn on a few central concepts. Knowing what they mean clarifies whether a carrier's handling may support a claim.
- The duty of good faith. Every policy obligates the insurer to deal fairly with the policyholder, and a breach of that duty lies at the heart of any bad faith claim.
- Reasonableness. The question is whether the carrier acted as a reasonable insurer would under the circumstances, not merely whether it ultimately paid.
- First-party versus third-party bad faith. Claims involving your own insurer differ from those arising when a carrier mishandles a claim brought against you.
- Statutory notice. Florida law requires a policyholder to put the carrier on formal notice before pursuing certain bad faith claims, giving the company a window to resolve the matter.
- Available remedies. A successful claim may reach beyond the original policy benefits, depending on the nature of the conduct and the harm it caused.
What Signs Point to Possible Bad Faith?
Certain patterns recur in cases where an insurer has failed its duty. Recognizing them early helps you decide whether to seek a closer review of your claim.
- Repeated requests for the same documentation without progress
- A denial that does not square with the policy language or the facts
- Long stretches of silence after the claim was reported
- A settlement offer far below the documented cost of repair
- An investigation that ignores evidence favorable to the policyholder
What Does a Bad Faith Claim Timeline Involve?
The path of a bad faith claim depends on the underlying dispute and the carrier's response, though most follow a recognizable sequence. Some resolve once the company faces formal notice. Others proceed well beyond that point.
- Resolution or determination of the underlying coverage claim
- Documentation of the carrier's handling and any unreasonable conduct
- Service of the statutory notice required under Florida law
- The carrier's opportunity to cure within the statutory window
- Negotiation, followed where necessary by litigation
What Should You Bring to Your Bad Faith Insurance Consultation?
Arriving prepared makes the first meeting far more productive. The more of the claim history we can review at the outset, the sooner we can assess whether the carrier's conduct supports a claim.
- The insurance policy and every communication exchanged with the carrier
- Denial, payment, or reservation-of-rights letters the insurer has issued
- A record of dates, calls, and correspondence throughout the claim
- Repair estimates, invoices, and documentation of the underlying loss
During the consultation, we will review the materials you provide, evaluate the carrier's handling of your claim, and offer a direct assessment of its strengths and challenges. We will outline your available options and the steps we would recommend moving forward, with no obligation on your part.
What Are Important Florida Legal Resources for Bad Faith Insurance Cases?
Several state and federal agencies publish guidance that helps policyholders understand their rights and locate the rules governing insurer conduct. The resources below provide reliable starting points for that research.
- The Florida Office of Insurance Regulation explains how homeowners insurance policies are structured and what coverage they generally provide.
- The same office offers consumer insurance tools for verifying a carrier's standing and researching its market conduct.
- For flood losses, the National Flood Insurance Program describes how to appeal a flood claim that an insurer has denied.
- The program also explains how to start a flood claim and what the process requires.
- After a declared disaster, federal support may be available through FEMA disaster assistance for losses a policy does not cover.
Florida law also sets deadlines for pursuing claims tied to insurer conduct and governs how damages are measured, so reviewing your policy alongside these resources early helps protect your rights.
Reach Out to The People's Law Team, PA Property Damage Lawyers to Schedule a Consultation
If your insurer has handled your claim unreasonably, our Fort Lauderdale bad faith insurance attorneys are prepared to review the carrier's conduct. The consultation is free, and because we work on contingency, you owe nothing unless we recover on your behalf. We will explain where your claim stands and how we can pursue accountability. Contact us to begin.
Bad Faith Insurance Statistics in Fort Lauderdale
 South Florida policyholders end up in court with their insurance carriers more often than property owners anywhere else in the state. The Florida Office of Insurance Regulation reported in its July 2026 stability report that Palm Beach, Broward, and Miami-Dade counties recorded a litigated rate of 27.27 percent on closed claims, more than three times the 8.16 percent rate across every other Florida county. Behind those filings are homeowners and business owners who concluded that a carrier's decision couldn't be squared with the policy they paid for.
Florida’s statewide figures reflect the same pattern. Although the state generated fewer than 5% of the nation’s homeowners insurance claims in 2025, it accounted for just over 41% of homeowners claim lawsuits filed across the country. Storm exposure drives a large share of that dispute volume, and Fort Lauderdale sits squarely in the path of it. The numbers below put the local picture in focus.
- Broward, Palm Beach, and Miami-Dade counties posted a 27.27 percent litigated rate on claims closed in 2025, against 8.16 percent everywhere else in Florida, according to the July 2026 stability report published by the Florida Office of Insurance Regulation.
- Florida produced under 5 percent of the country's homeowners insurance claims in 2025 but just over 41 percent of the related lawsuits, per the same state report.
- NOAA disaster records confirm 94 separate billion-dollar weather disasters struck Florida from 1980 through 2024, including 36 tropical cyclone events.
- Fort Lauderdale is home to 182,760 residents as of the 2020 count, Census Bureau data shows, nearly all of them relying on some form of property coverage.
Mistakes That Can Damage Your Bad Faith Insurance Claim
A bad faith case rises or falls on the record. The carrier's conduct matters, but so does yours, because the insurer's defense lawyers will comb through every step you took after the loss. Our Fort Lauderdale bad faith insurance lawyers see the same avoidable errors weaken otherwise strong claims. Here are the ones that cause the most damage.
- Reporting the loss late or incompletely. Delay gives the carrier its favorite defense. Report promptly, follow the steps for filing a claim carefully, and keep proof of when and how you reported.
- Communicating only by phone. Verbal promises from an adjuster vanish when the claim turns contested. Put requests and responses in writing, and follow up phone calls with a short confirming email. If it isn't documented, the carrier will act as though it never happened.
- Failing to track the adjuster's conduct. The claims adjustment process generates the evidence that later proves unreasonable handling. Save every letter, log every inspection date, and note every promise that went unkept.
- Accepting the first low offer. Cashing a settlement check can end your leverage before you understand the full scope of the loss. Underpaid claims are often the foundation of a bad faith case, but only if the policyholder didn't sign that foundation away.
- Guessing at what the policy says. Coverage arguments start with the contract. Reading your homeowner's insurance policy, including its endorsements and exclusions, prevents the carrier from mischaracterizing what it owes.
- Waiting silently while the carrier stalls. Months of inaction hurt you twice. The damage worsens, and the insurer later argues you took too long on your rights. Delayed claims should be met with written demands for a decision, not patience.
- Making repairs before documentation is complete. Fix what safety requires, and nothing more, until the damage is photographed, measured, and independently estimated. Discarded evidence cannot be recovered.
- Exaggerating any part of the claim. One inflated line item gives the carrier cover to question everything else. Accuracy protects your credibility, and your credibility is an asset the insurer cannot take from you.
- Bringing in counsel after the record is already made. Knowing when to hire a lawyer matters, and the honest answer is early.
Fort Lauderdale Bad Faith Insurance Lawyer FAQs
How much does a bad faith insurance attorney in Fort Lauderdale cost?
Nothing up front. We handle bad faith insurance cases on contingency, so there's no retainer and no hourly billing. Our fee comes out of the recovery, and if there is no recovery, you owe us nothing. Policyholders should never have to fund a legal fight against a national carrier out of pocket.
Can I sue my insurance company for bad faith in Florida?
Yes. Florida recognizes claims against insurers that fail to handle valid claims fairly and honestly. State law requires formal notice to the carrier before certain bad faith actions proceed, and the company receives a window to cure its conduct. A Fort Lauderdale bad faith insurance attorney can evaluate whether your carrier's handling supports a claim.
What is the difference between a denied claim and bad faith?
A denial can be wrong without being bad faith. The question is whether the carrier's decision was reasonable given the policy and the facts. Our coverage dispute work addresses whether the loss was covered. Bad faith addresses how the insurer treated you while deciding.
How long do I have to act on a bad faith claim?
Florida law sets deadlines both for the underlying insurance claim and for actions tied to the carrier's conduct, and missing either one can end your rights. The safest course is a prompt review. We can identify the deadlines that apply to your specific situation during a free consultation.
Do I have to resolve my coverage dispute before pursuing bad faith?
Usually the underlying claim comes first. Bad faith remedies typically depend on establishing that the carrier owed benefits it failed to pay reasonably. Handling denied and delayed claims alongside the bad faith evidence lets us build both records at once rather than starting over later.
What compensation can a bad faith case recover?
A successful claim may reach beyond the original policy benefits. Depending on the conduct and the harm it caused, recovery can include the full value of the covered loss along with additional damages Florida law makes available. The specific remedies turn on the facts of the carrier's handling.
Does bad faith law protect commercial policyholders?
It does. Businesses hold the same right to fair claim handling that homeowners do, across the types of damage a commercial policy covers. Carriers sometimes assume a business will absorb an underpayment rather than fight. We represent commercial policyholders in Fort Lauderdale, FL who refuse to.
Are hurricane claims treated differently?
The duty of good faith applies with equal force after a storm. Hurricane damage claims often involve heavy claim volume, rushed inspections, and disputed causation, and each of those pressures can produce the unreasonable handling that supports a bad faith case.
Will my bad faith case go to trial?
Many resolve after the statutory notice or through negotiation. Some don't. We prepare every case as though a Broward County jury will decide it, because carriers pay attention to firms with verdicts. Our record includes trial wins against major Florida insurers.
Where can I research my rights before hiring anyone?
Start with the state's own materials. Florida publishes government resources for property owners covering claim rights, carrier complaints, and consumer protections. Reviewing them costs nothing and helps you ask sharper questions during your consultation with a Fort Lauderdale, FL bad faith insurance lawyer.
Local Resources for Fort Lauderdale Bad Faith Insurance Cases
Local agencies hold records and services that support a disputed claim, from court filings to permit histories that document repairs. These offices serve Fort Lauderdale policyholders directly.
- Broward County Clerk of Courts: Where insurance lawsuits in the county are filed and case records are kept, (954) 831-6565.
- City of Fort Lauderdale Development Services: Which issues the building permits and inspection records that document storm repairs, (954) 828-8000.
- Broward County Property Appraiser: The source for official property records and valuation history on a damaged home or building, (954) 357-6830.
These organizations are listed for informational purposes only. We do not endorse them, and no affiliation exists between these entities and our firm.
About The People's Law Team, PA Property Damage Lawyers
We have won 99 percent of our cases for Florida policyholders, a record built one disputed claim at a time. In 2026, our firm took Universal Property to trial, won, and then defeated the carrier's appeal. If you are currently dealing with a bad faith insurer, we recommend acting quickly so our team can intervene.
What Our Clients Say
⭐⭐⭐⭐⭐
"I had a great experience with The People's Law Team. Even though the Citizens law team was dragging their feet with never ending unreasonable depositions, Maria and her team stayed persistent and made sure I got the compensation I deserved. They explained every detail clearly, answered my questions promptly, and were genuinely supportive throughout the process. I appreciated how down-to-earth and approachable they were, which made a tough situation much easier to handle. I truly felt they were on my side every step of the way. I'm really grateful for their help and highly recommend them!" - Jonathan Troche
Read more reviews on our Google Business Profile.
Additional Resources for Fort Lauderdale, FL Bad Faith Insurance Cases
- What Is "Late Reporting" and How Can We Defeat That Defense When the Insurance Company Attacks Property Owners on That Basis?
- When Insurance Company Claims Water Loss Is Long-Term Seepage/Leakage
- The People's Law Team Wins Trial Against Universal Property and Defeats Their Appeal in 2026
Contact The People's Law Team, PA Property Damage Lawyers
An insurer that mishandled your claim is counting on you to accept it. Our Fort Lauderdale bad faith insurance attorneys will review the carrier's conduct, explain where your claim stands, and pursue every remedy Florida law allows. The consultation is free, we work on contingency, and you'll pay no out-of-pocket legal costs at any point. We keep clients informed at every stage. Contact us today to schedule your free consultation.