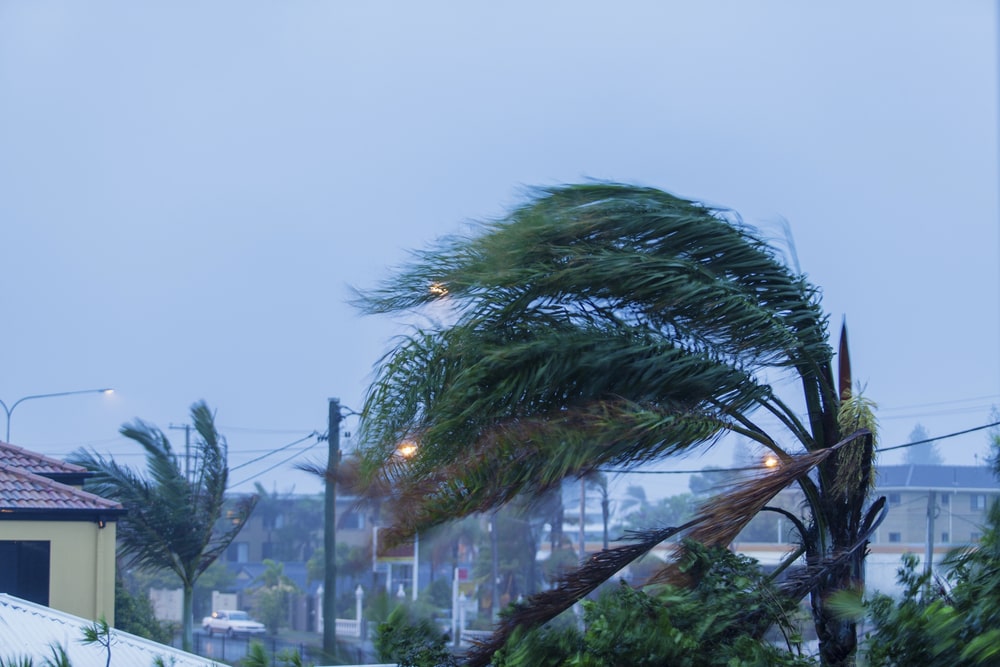
Hurricane Isaias made landfall near Destin as a Category 2 storm, and property owners across the Panhandle are now assessing roof, wind, and water damage. The steps you take in the first few weeks can shape how your insurance claim is handled. Acting carefully now protects both your property and your claim.
Document the Damage Before Repairs
Photograph and video every affected area before anything is moved or repaired. Capture wide shots of each room as well as close views of specific damage.
News coverage of the storm described roofs and facades torn from buildings in Pensacola and Panama City Beach. Interior damage is easy to miss. Water can travel behind drywall and under flooring, and insurers often argue later that the stains came from seepage and leakage that existed before the storm.
Keep a record of the following items.
- Photographs and videos should show each damaged area before cleanup.
- Receipts should cover tarps, water extraction, lodging, and other emergency costs.
- Damaged materials should stay on site until the adjuster has seen them, when it is safe to keep them.
- A written log should note every call, email, and visit from the insurer.
Make Reasonable Emergency Repairs
Most policies require you to protect the property from further damage. Covering a damaged roof or removing standing water is usually expected, while permanent repairs can generally wait until the insurer has inspected.
These temporary measures are a routine part of hurricane disaster damage claims, and their cost is often recoverable.
Report the Claim Promptly
Under section 627.70132, Florida Statutes, notice of a hurricane claim must be given within one year of the date the hurricane made landfall. A supplemental claim must be reported within 18 months.
Waiting rarely helps. Insurers frequently raise a late reporting defense when notice comes months after a storm.
Know the Insurer's Deadlines
Florida law also places deadlines on your insurer. Section 627.70131 requires residential property insurers to acknowledge claim communications within seven days, inspect within 30 days of receiving proof of loss, and pay or deny the claim within 60 days of notice. Missed deadlines and low offers are common in denied and delayed claims after a major storm.
Coverage limits, the hurricane deductible, and flood exclusions all affect homeowner property damage claims, so read your policy before the adjuster arrives.
A Florida Hurricane Isaias Florida property damage lawyer can compare the insurer's estimate with your contractor's numbers and identify what was left out.
Getting Help With Your Claim
If Hurricane Isaias damaged your home or business, The People's Law Team, PA Property Damage Lawyers can review your policy and claim as it develops. Contact our office to speak with a Florida Hurricane Isaias Florida property damage lawyer about your next steps.